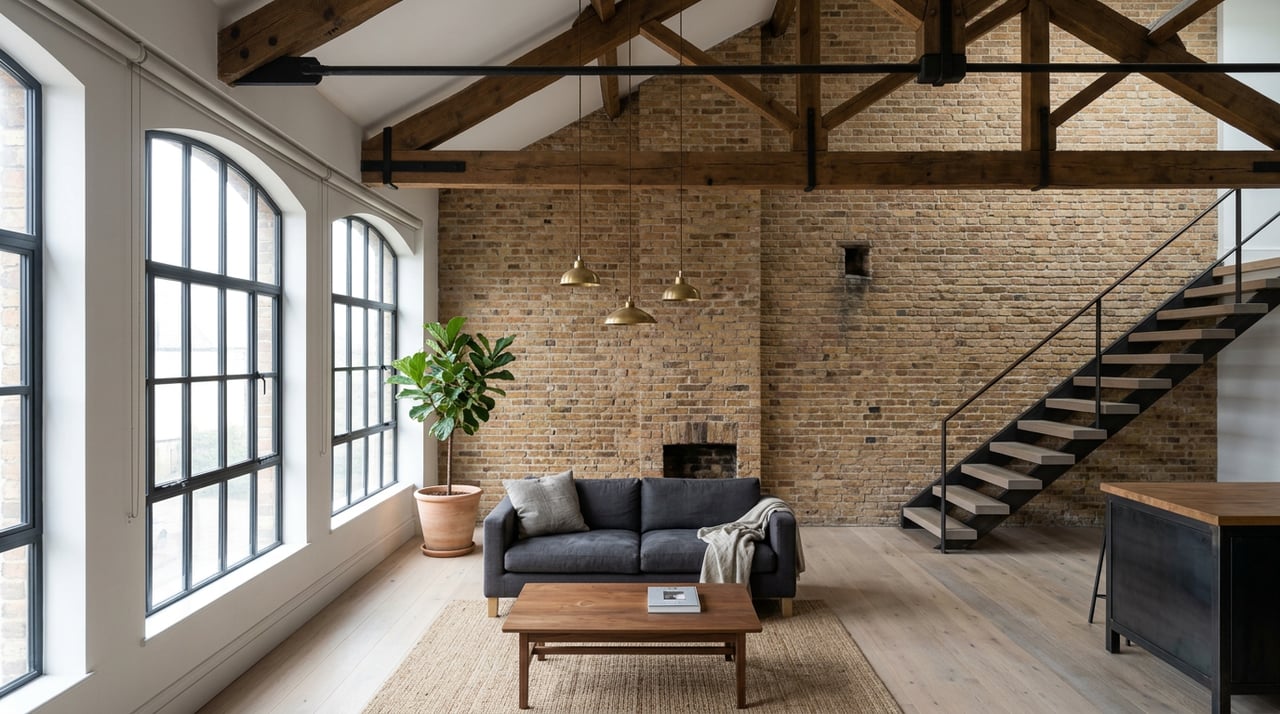
Ask most buyers touring a loft at Carriage Lofts on Millyard whether Amesbury counts as a coastal town, and they will say no. It sits inland along the Powow River, a mill town with brick facades and cast iron radiators, six miles from the nearest beach. But Massachusetts does not define "coastal" by whether you can see the ocean from your kitchen window. It defines it by watershed and jurisdiction, and under that definition, Amesbury has been coastal for decades. That distinction used to be a bureaucratic footnote. As of this year, it is something every buyer closing on a mill conversion in the Millyard needs to understand before they sign a purchase and sale agreement.
Two regulatory changes converged in the past eighteen months to make this real. The first is a new statewide insurance disclosure. The second is a rule that treats Amesbury the same way it treats Nahant or Gloucester when it comes to flood coverage. Neither one is theoretical, and neither one is something a standard home inspection will catch.
The Notice Now Riding Along With Every Policy
Starting with any homeowners or dwelling policy issued or renewed on or after January 1, 2026, Massachusetts insurers are required to include a standalone disclosure page, positioned directly after the declarations page, stating in plain language that the policy does not cover flood damage. The Division of Insurance specified the exact language carriers must use, including a line telling policyholders that their agent or the Division itself can provide more information about flood coverage.
For a single-family buyer in, say, West Newbury, that notice is a formality. Their policy already excluded flood, this just makes it explicit. For a buyer closing on a unit at 25 Pond Street or 37 Millyard, it lands differently, because the building itself sits feet from a river with a documented flood history, inside a condo association whose master policy most buyers never actually read before closing.
Why the Millyard Falls Under Coastal Rules
Here is the part that surprises people. Massachusetts' Office of Coastal Zone Management maintains a list of 78 communities it classifies as coastal, organized into five regional programs. The North Shore region runs from Salisbury down through Revere, and Amesbury is on that list, grouped with Newburyport, Salisbury, Rowley, and Ipswich, not because of ocean frontage but because it sits within the Merrimack and Parker River watersheds that CZM was chartered to manage.
That classification matters because of a separate rule from the Massachusetts Property Insurance Underwriting Association. Under MPIUA Rule A10, effective for new business written on or after February 1, 2025, any property sitting inside a federally designated Special Flood Hazard Area within one of those 78 coastal communities must carry flood insurance as its own separate policy, distinct from the homeowners or condo policy, with proof of that coverage submitted within 30 days of binding. The rule does not distinguish between a shingled house on Plum Island and a converted brick mill on the Powow River. If the parcel sits in a mapped flood zone inside a CZM community, the rule applies.
This is the mechanism that turns a river-town condo purchase into a two-policy transaction. Buyers who assume "Amesbury isn't coastal" skip the flood-zone check that a Salisbury or Newburyport buyer would run reflexively, and that is exactly the gap Rule A10 was written to close.
What the Math Actually Looks Like
Here is where the numbers stop being abstract. The National Flood Insurance Program caps building coverage at $250,000 per unit for residential condominiums, with a separate $100,000 cap on contents. That ceiling was set with a national housing stock in mind, not Amesbury's Millyard, where recent sales tell a different story:
| Address | Sold Price | Sale Date | NFIP Building Cap | Approximate Coverage Gap |
|---|---|---|---|---|
| 39 Millyard #202 | $412,500 | August 2026 | $250,000 | $162,500 |
| 25 Pond Street #210 | $499,900 | May 2026 | $250,000 | $249,900 |
| 37 Millyard #206 | $380,000 | May 2025 | $250,000 | $130,000 |
If any of these units sat in a mapped Special Flood Hazard Area and suffered a total flood loss, the federal program's per-unit ceiling would not come close to covering the rebuild cost at current sale values. That gap does not disappear because the building has a master insurance policy through the condo association. Master policies typically insure the building's common structure and shared systems, not an individual owner's finished interior, upgraded kitchen, or personal property, and they are subject to their own limits and exclusions that vary by association.
This is the argument for reading the HOA's insurance documents before writing an offer, not after. A buyer who only checks their own future flood policy and skips the master policy is looking at half the exposure.
The Flood Is Not Hypothetical
None of this is a distant risk scenario. In May 2006, a slow-moving storm dropped record rainfall across New England, and the Powow River rose through Amesbury's Millyard over May 14 and 15, flooding the same stretch of riverbank where these mill buildings now sit as condominiums. Local footage from that weekend, archived online, shows the water reaching streets and building foundations in the exact district where Carriage Lofts and The Lofts at Clark's Pond operate today. The dam-and-mill geography that made the Powow attractive to 19th century industrialists, an 80-foot elevation drop concentrated in a quarter mile, is the same geography that concentrates floodwater when the river runs high.
That history is precisely why CZM's watershed-based definition of coastal makes engineering sense even when it defies the postcard image of the word.
What to Ask Before You Write the Offer
A buyer working with informed representation on a Millyard mill loft should be asking for a specific set of documents before the offer stage, not during the inspection contingency:
- The condo association's current master insurance policy and its stated flood coverage, if any
- The most recent reserve fund study and any pending special assessments tied to flood or water damage
- A building-specific FEMA flood zone determination, since large mill complexes can straddle zone boundaries between units in the same building
- Whether the specific unit falls within a Special Flood Hazard Area, which would trigger the MPIUA Rule A10 requirement for a standalone flood policy
- A realistic quote for that standalone policy before the mortgage contingency deadline, since lenders will require proof of coverage before closing on any property in a mapped zone
None of this changes the appeal of these buildings. The exposed brick, the timber ceilings, the walk to the Powow Riverwalk and downtown's restaurants and breweries are real, and they are a large part of why these units continue to sell close to asking. What has changed is the paperwork trail between an accepted offer and a clean closing, and that trail now runs through two state-level rules that did not exist in this form two years ago.
A Few Questions Worth Answering Directly
Does this apply to every unit in a mill building, or just some? It depends on where the specific unit sits relative to the mapped flood zone boundary. Large mill complexes were often built in phases and can straddle a Special Flood Hazard Area line, so two units in the same building can have different requirements.
Is the January 2026 disclosure the same thing as flood insurance? No. The disclosure is a notice confirming that a standard policy does not cover flood loss. It does not provide coverage on its own. A separate flood policy, through the NFIP or a private carrier, is what actually pays a claim.
Does the condo association's master policy cover my unit's flood risk? Master policies vary by association and typically focus on shared structure, not an individual owner's interior finishes or contents. Reviewing the actual policy document, not just the HOA's summary, is the only way to know what it covers.
Buying in Amesbury's Millyard rewards buyers who treat the insurance conversation as part of the offer strategy, not an afterthought handled after mortgage approval. Alissa Christie works with buyers across Amesbury and the North Shore who want that kind of groundwork done before an offer goes in, not discovered during underwriting. Let's connect.